Back to Blog
Fintech & PaymentsFintech and payment
Unpacking IFC’s $700 Million Risk-Sharing Initiative and the POS Fintech Boom
Emmanuel Clifford Gyetuah·September 20, 2026·7 min
Fintech & Payments
Over the past decade, traditional brick-and-mortar banking models have increasingly given way to digital financial services (DFS) , driven by mobile technology, agency banking, and fintech innovations. Despite this rapid momentum, a critical bottleneck has persisted: the high capital and settlement risk requirements imposed by global payment networks on local financial institutions, banks, and fintechs.
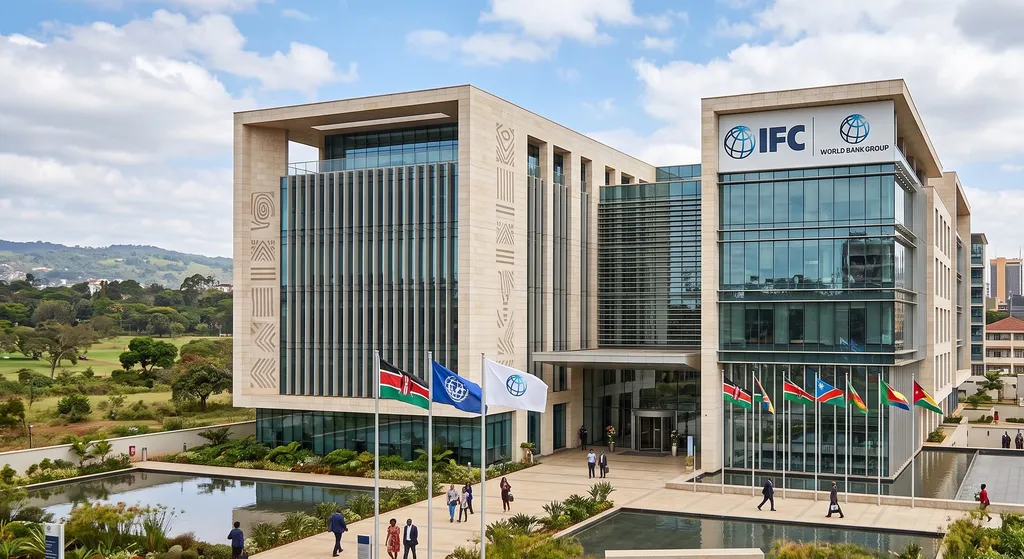
To directly confront this systemic challenge, the International Finance Corporation (IFC), a member of the World Bank Group, recently launched a landmark $700 million Digital Payments Risk-Sharing Initiative . Operating in strategic partnership with global payment giants Mastercard and Visa, this initiative provides risk-guarantee structures designed to de-risk participating local financial institutions.
By mitigating credit settlement risk, this initiative is poised to unlock immense economic potential across developing markets. IFC estimates indicate that participating financial institutions could generate approximately $280 billion in additional digital payment volumes, issue over 360 million new payment cards, and bring 90 million new active users, including at least 39 million women, into the formal digital economy.
For industry stakeholders, software developers, regulators, and digital economy observers following the Africa Digital Forum, this initiative represents far more than a headline figure. It serves as a vital structural catalyst for financial ecosystems. In particular, financial technology companies specializing in Point-of-Sale (POS) machine deployment and merchant acquiring stand to gain exponentially. By expanding market liquidity, lowering reserve burdens, and enabling mass card issuance, this facility creates unprecedented opportunities to convert cash-based economies into formal, bank-integrated digital networks.
Unpacking Credit Settlement Risk
To understand why a $700 million risk-sharing facility is transformative, one must first understand the mechanics of credit settlement risk in international and domestic card payment ecosystems.
When a consumer taps or swipes a card at a merchant POS terminal or uses a mobile app, a complex series of backend transactions occurs between the issuing bank (the bank that issued the consumer’s card), the acquiring institution (the bank or fintech managing the merchant's POS terminal), and the card scheme network (such as Visa or Mastercard).
Between the time a transaction is authorized and when final settlement funds are cleared, there is a delay. During this window, card scheme networks face settlement risk, the risk that a participating bank or fintech will fail to honor its financial settlement obligations due to insolvency, operational failure, or currency liquidity shortages.
To hedge against this exposure, global networks traditionally mandate that participating local banks and fintechs maintain substantial cash collateral, security deposits, or standby letters of credit. For many emerging market financial institutions, especially high-growth fintechs operating in volatile currency environments, locking up millions of dollars in non-earning collateral creates a severe liquidity drag. This requirement limits their capacity to issue cards, deploy new payment terminals, or expand merchant networks, leaving vast segments of consumers and small business owners dependent on cash.
How the IFC Risk-Sharing Mechanism Works
The IFC initiative intervenes directly at this structural pain point by providing partial credit guarantees.
- Risk Absorption: IFC absorbs a designated portion of the credit settlement risk that local participating banks and fintechs present to the global payment networks.
- Capital Unlocking: Because the risk is partially guaranteed by triple-A/multilateral entities, payment networks can significantly reduce the cash collateral or collateral reserves required from local institutions.
- Capacity Expansion: Local banks and fintechs regain access to trapped balance-sheet liquidity, which can immediately be reallocated toward expanding local operations, funding agent networks, issuing cards, and onboarding micro, small, and medium enterprises (MSMEs).
Why POS-Specialized Fintechs are Strategic Beneficiaries
Point-of-Sale (POS) terminal issuance and merchant acquiring form the physical backbone of digital payments in many developing economies, especially across sub-Saharan Africa. While mobile apps and USSD channels serve personal peer-to-peer (P2P) transfers, POS machines bridge the gap between digital wallets, bank cards, and real-world commercial trade at physical retail points.
Fintechs specializing in POS deployment stand to benefit immensely from the IFC risk-sharing framework in several key ways:
1. Market Expansion and Increased Transaction Volume
By backing $280 billion in additional digital payment volume and 360 million new cards, the initiative directly expands the addressable market for POS acquiring fintechs. A card cannot function without an operational terminal, and a terminal is useless without cards in circulation. By accelerating card issuance on a massive scale, the initiative creates immediate demand for POS terminals across retail outlets, kiosks, and service centers.
2. Deeper Integration with Bank Transactions
POS terminals managed by fintechs operate as critical bridges to formal banking networks. Transactions processed on POS terminals do not merely move money; they generate structured bank records, provide data trails for credit scoring, and drive velocity through settlement accounts held at commercial banks. As POS networks scale, the velocity of interbank and intra-bank transactions increases, strengthening overall system liquidity and bringing informal cash into formal bank channels.
3. Lowering Capital Barriers for Merchant Onboarding
Deploying physical POS hardware requires capital expenditure, device management, and liquidity reserves to fund real-time merchant payouts before interbank clearing takes place. Reduced collateral requirements free up working capital for fintechs, allowing them to subsidize hardware costs, lower acquiring fees for micro-merchants, and extend terminal distribution into rural and peri-urban areas.
Case Study: PalmPay and the Agency Banking Transformation
A clear illustrative example of how POS-specialized fintechs drive financial inclusion in Africa is PalmPay .
Founded with a vision to build an inclusive digital financial ecosystem, PalmPay has become one of West Africa’s most prominent fintech success stories, particularly in Nigeria. PalmPay operates a dual-pronged model combining a consumer-facing digital wallet application with an extensive agency banking and merchant POS network.
The Role of PalmPay POS Terminals in Daily Commerce
In markets like Nigeria, where cash accessibility at traditional bank ATMs has experienced periodic disruptions, PalmPay deployed hundreds of thousands of POS terminals to merchant points, corner shops, and neighborhood agents.
Human ATMs (Cash-In / Cash-Out): Neighborhood merchants act as financial access points where individuals can deposit cash into bank accounts or withdraw cash using debit cards or mobile transfers.
Merchant Acquiring: Small retailers, grocery stores, and service providers use PalmPay POS machines to accept direct card payments from customers, reducing the risks and security overheads associated with holding physical cash.
Instant Bank Settlements: PalmPay leverages real-time transaction processing infrastructure, ensuring merchants receive instant value for sales made via POS, which builds crucial trust among informal traders.
Leveraging Risk-Sharing Mechanisms for Next-Gen Scaling
For an enterprise operating at the scale of PalmPay, participating in global card ecosystems and maintaining high-volume settlement capabilities requires immense balance-sheet management.
Under an initiative like the IFC risk-sharing guarantee:
- Accelerated Card Issuance: PalmPay and similar fintechs can issue millions of co-branded or scheme payment cards (debit, prepaid, or virtual) directly to their wallet users with lower reserve obligations.
- Terminal Network Expansion: Capital previously tied up as risk collateral can be re-invested into procuring and distributing next-generation Android POS hardware, supporting sound, QR code, and contactless payment methods.
- Enhanced Interoperability: Lower settlement barriers enable fintechs to deepen interoperability with traditional commercial banks, facilitating seamless transfers, card processing, and credit access across multi-bank networks.
As a result, an agent operating a PalmPay POS terminal in a rural market becomes an active node in a $280 billion global payment flow, connecting a rural buyer directly to global financial rails.
Ecosystem Quality, Competition, and Policy Implications
The influx of $700 million in risk guarantees into emerging market digital payment channels carries wider strategic implications for regulators, policymakers, and financial ecosystem architects.
Boosting Competition and Service Quality
When high collateral hurdles are removed, market entry barriers fall. Smaller and medium-sized fintechs can compete more effectively alongside legacy commercial banks. This heightened competition drives innovation in payment processing technology, lowers fee structures for merchants, and encourages the development of higher-quality user interfaces and customer protection mechanisms.
Strengthening Regulatory Confidence
For central banks, such as the Bank of Ghana or the Central Bank of Nigeria, initiatives backed by multilateral bodies like the IFC offer reassuring risk-mitigation frameworks. By channeling transaction flows through secure, guaranteed card and digital payment rails, central banks gain better visibility into monetary velocity, anti-money laundering (AML) compliance, and consumer protection adherence.
Building a Connected, Prosperous Digital Africa
The launch of the IFC’s $700 million Digital Payments Risk-Sharing Initiative marks a decisive milestone in global financial inclusion efforts. By tackling the quiet yet formidable challenge of settlement risk, this initiative frees up capital, lowers friction, and provides the liquidity necessary to build truly inclusive payment networks.
For POS-specialized fintechs like PalmPay and the broader African digital finance ecosystem, the path ahead is clear. As millions of new cards are issued and millions of merchants adopt digital acquiring terminals, informal trade will increasingly merge with formal banking channels.
At the Africa Digital Forum , we believe that true digital transformation occurs when technology directly empowers everyday citizens, merchants, and entrepreneurs. With enhanced risk-sharing structures in place, Africa's digital economy is positioned to accelerate rapidly, turning payment terminals into catalysts for sustainable economic growth and financial dignity across the continent.
EC
Emmanuel Clifford Gyetuah
Emmanuel Clifford Gyetuah is a versatile leader who specializes in transforming complex financial metrics into actionable strategic insights. Currently, he is the Organizing Director for the Africa Digital Forum, Director at the Media and Digital Institute, and Senior Finance Manager at Bolingo Consult.